(Attribution)
How to read a cohort report.
Compare B2B acquisition cohorts using consistent windows, verified percentage changes, attribution rules and clear metric definitions.
(Introduction)
Before the revenue review, open a cohort row and trace an account back to its entry event. Check the date, source, opportunity, and current status. A report that cannot explain a single row needs a data review before it can support a budget decision.
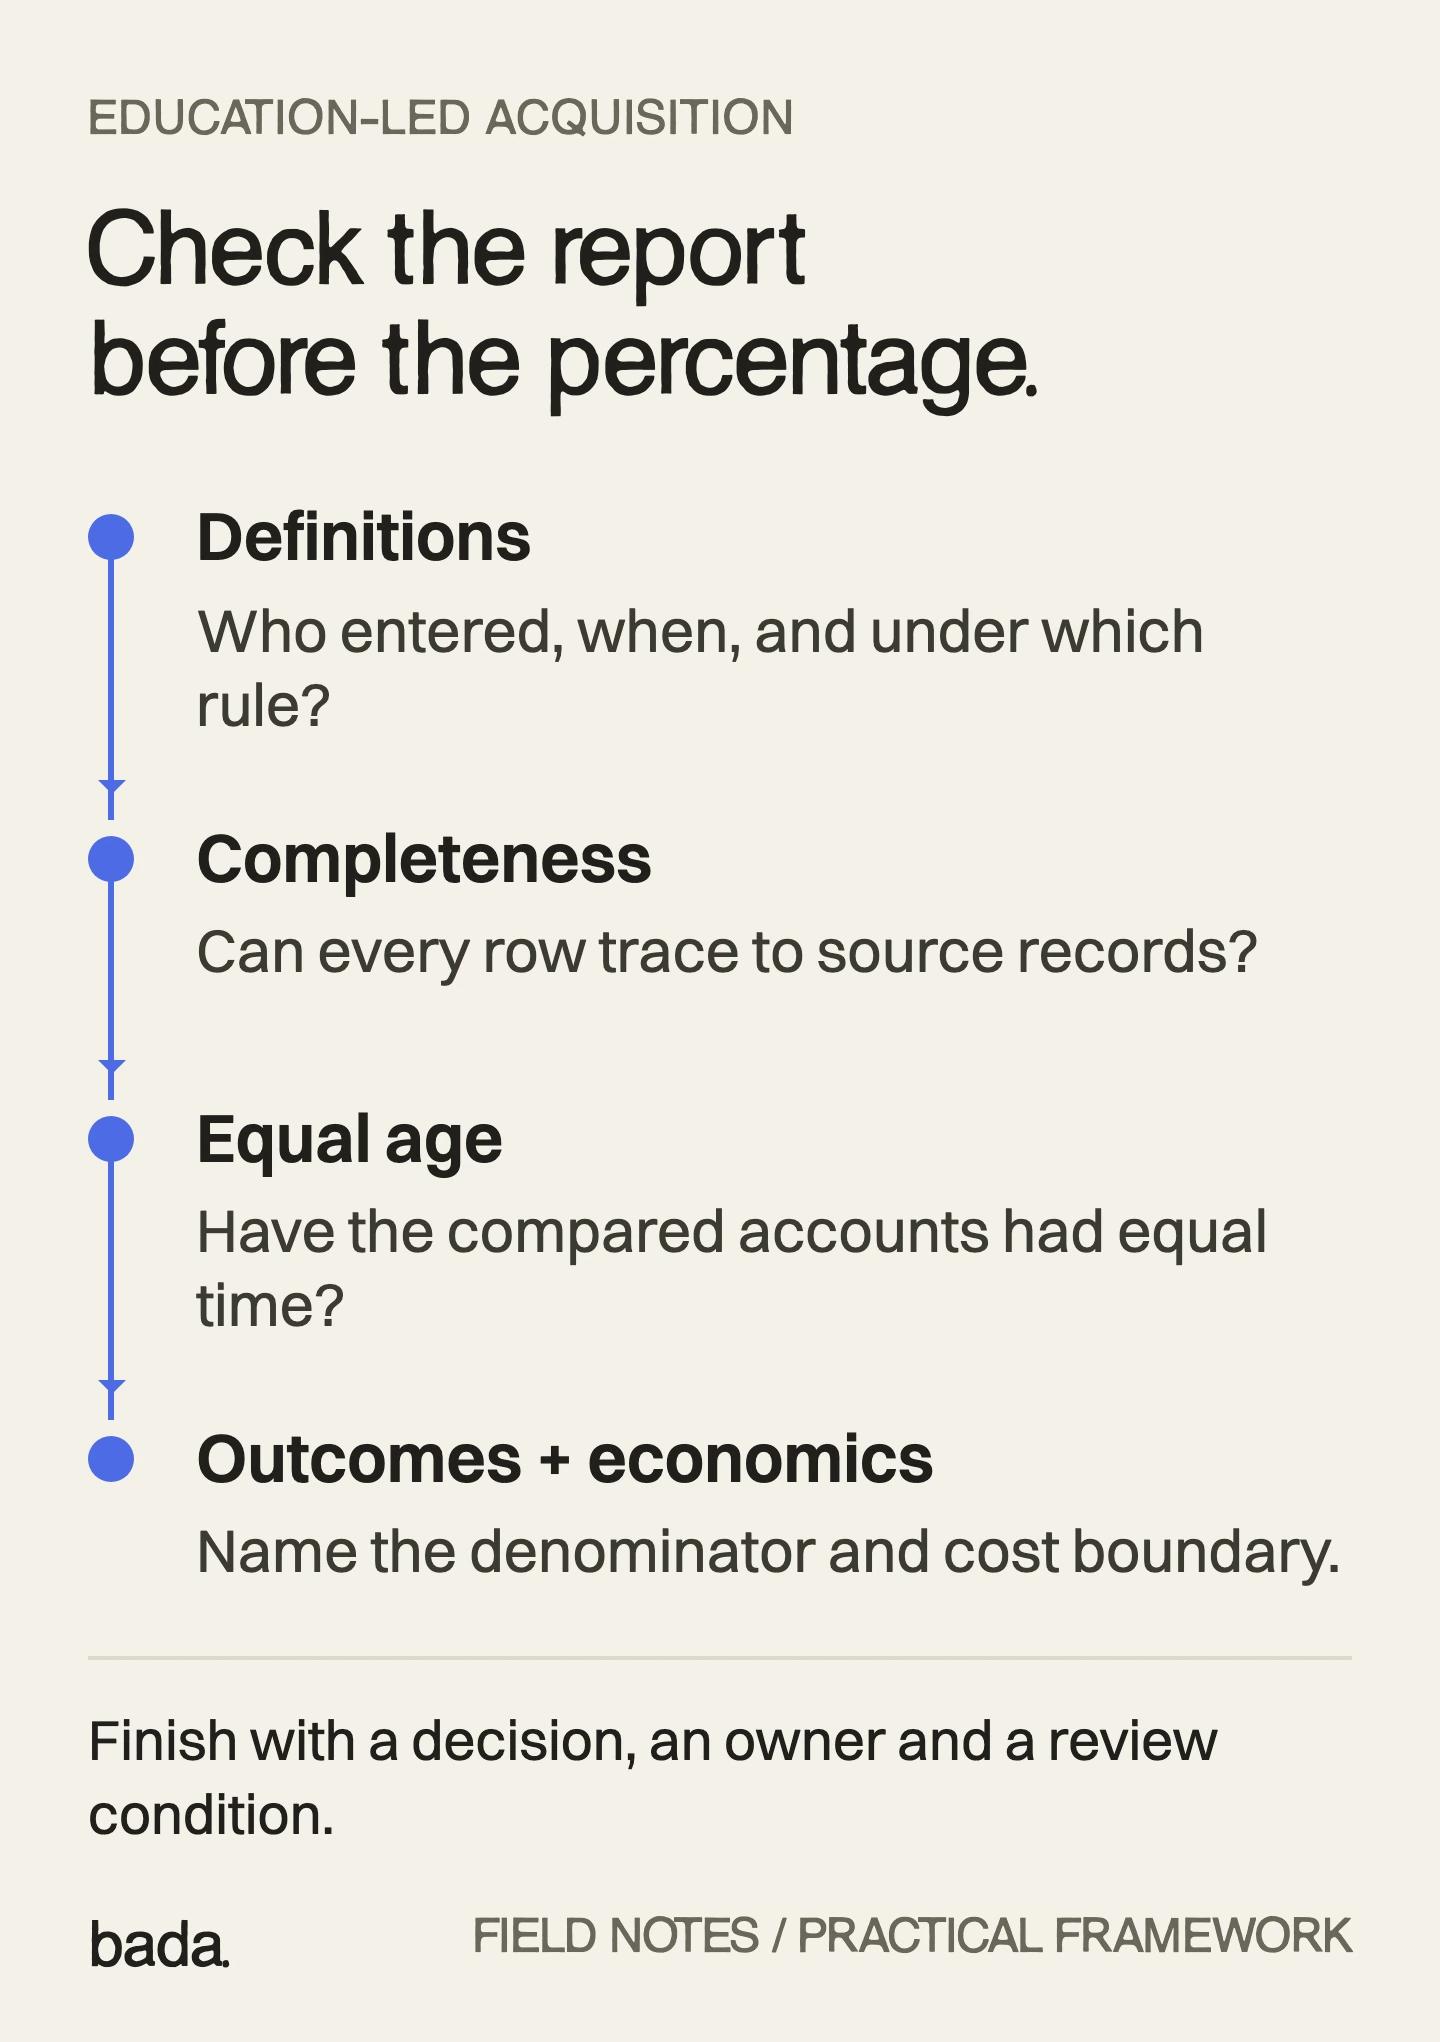
Once that connection is sound, read the report in a fixed order: definitions, completeness, age, outcomes, economics, and action. The sequence keeps an attractive percentage from deciding the meeting before anyone checks what it contains.
If you need the rationale for this view, start with why we measure cohorts. This guide covers the operating review.
(1. Read the metric contract)
Ask RevOps to put the report's rules beside the report. A metric contract is a short agreement about what each field means. It should cover:
- Membership: the account or person being counted, the entry event, entry window, exclusions, and deduplication rule.
- Time: the reporting cutoff, timezone, elapsed-age calculation, and whether each metric is cumulative or a current-state snapshot.
- Outcomes: the definition of an accepted opportunity, closed-won status, closed-lost status, and the amount field used for bookings or revenue.
- Attribution and cost: the source assignment rule, influence criteria, unknown-source treatment, and included costs.
Name the denominator for every rate. Accounts that generated an opportunity divided by acquired accounts is an account-to-opportunity rate. Won opportunities divided by decided opportunities is a decided-opportunity win rate. Labeling both as conversion rate hides a material difference.
Keep the definitions stable across the comparison. Annotate changes that require a new baseline.
(2. Check whether the report is ready to read)
Reconcile cohort membership with the underlying entry records. Check that opportunity links, stage histories, and cost imports are complete through the stated cutoff. Confirm that duplicate contacts from one account do not create duplicate wins.
Show the counts and share of records missing each required field. Missing acquisition source should remain unknown. Missing revenue should remain unknown. A zero belongs in the report only when the relevant records were checked and the measured result was zero.
Separate observed history from reconstructed history. If the system only stores current stages, it may be unable to tell you where an account stood at an earlier age. Label that limitation and repair it before claiming an equal-age comparison.
Do not rank channels whose data is materially incomplete. Assign an owner to the missing join or import first.
(3. Align the observation window)
Compare cohorts at the same age from each member's entry event. A cohort acquired earlier can have a longer lifetime view, but that view cannot fairly stand beside a newer cohort's shorter observation window.
Use only members who have reached the chosen age, and display the eligible count. If part of a monthly cohort is still too young, label the result partial or wait until all members are eligible. Never fill future-age cells with zero.
Check the scope before reporting growth
The Athena Ag case describes the system around its educational material: webinar and Commercial Handbook offers, paid distribution and CRM measurement. Use that operating structure to define which program interactions and outcomes belong in the report.
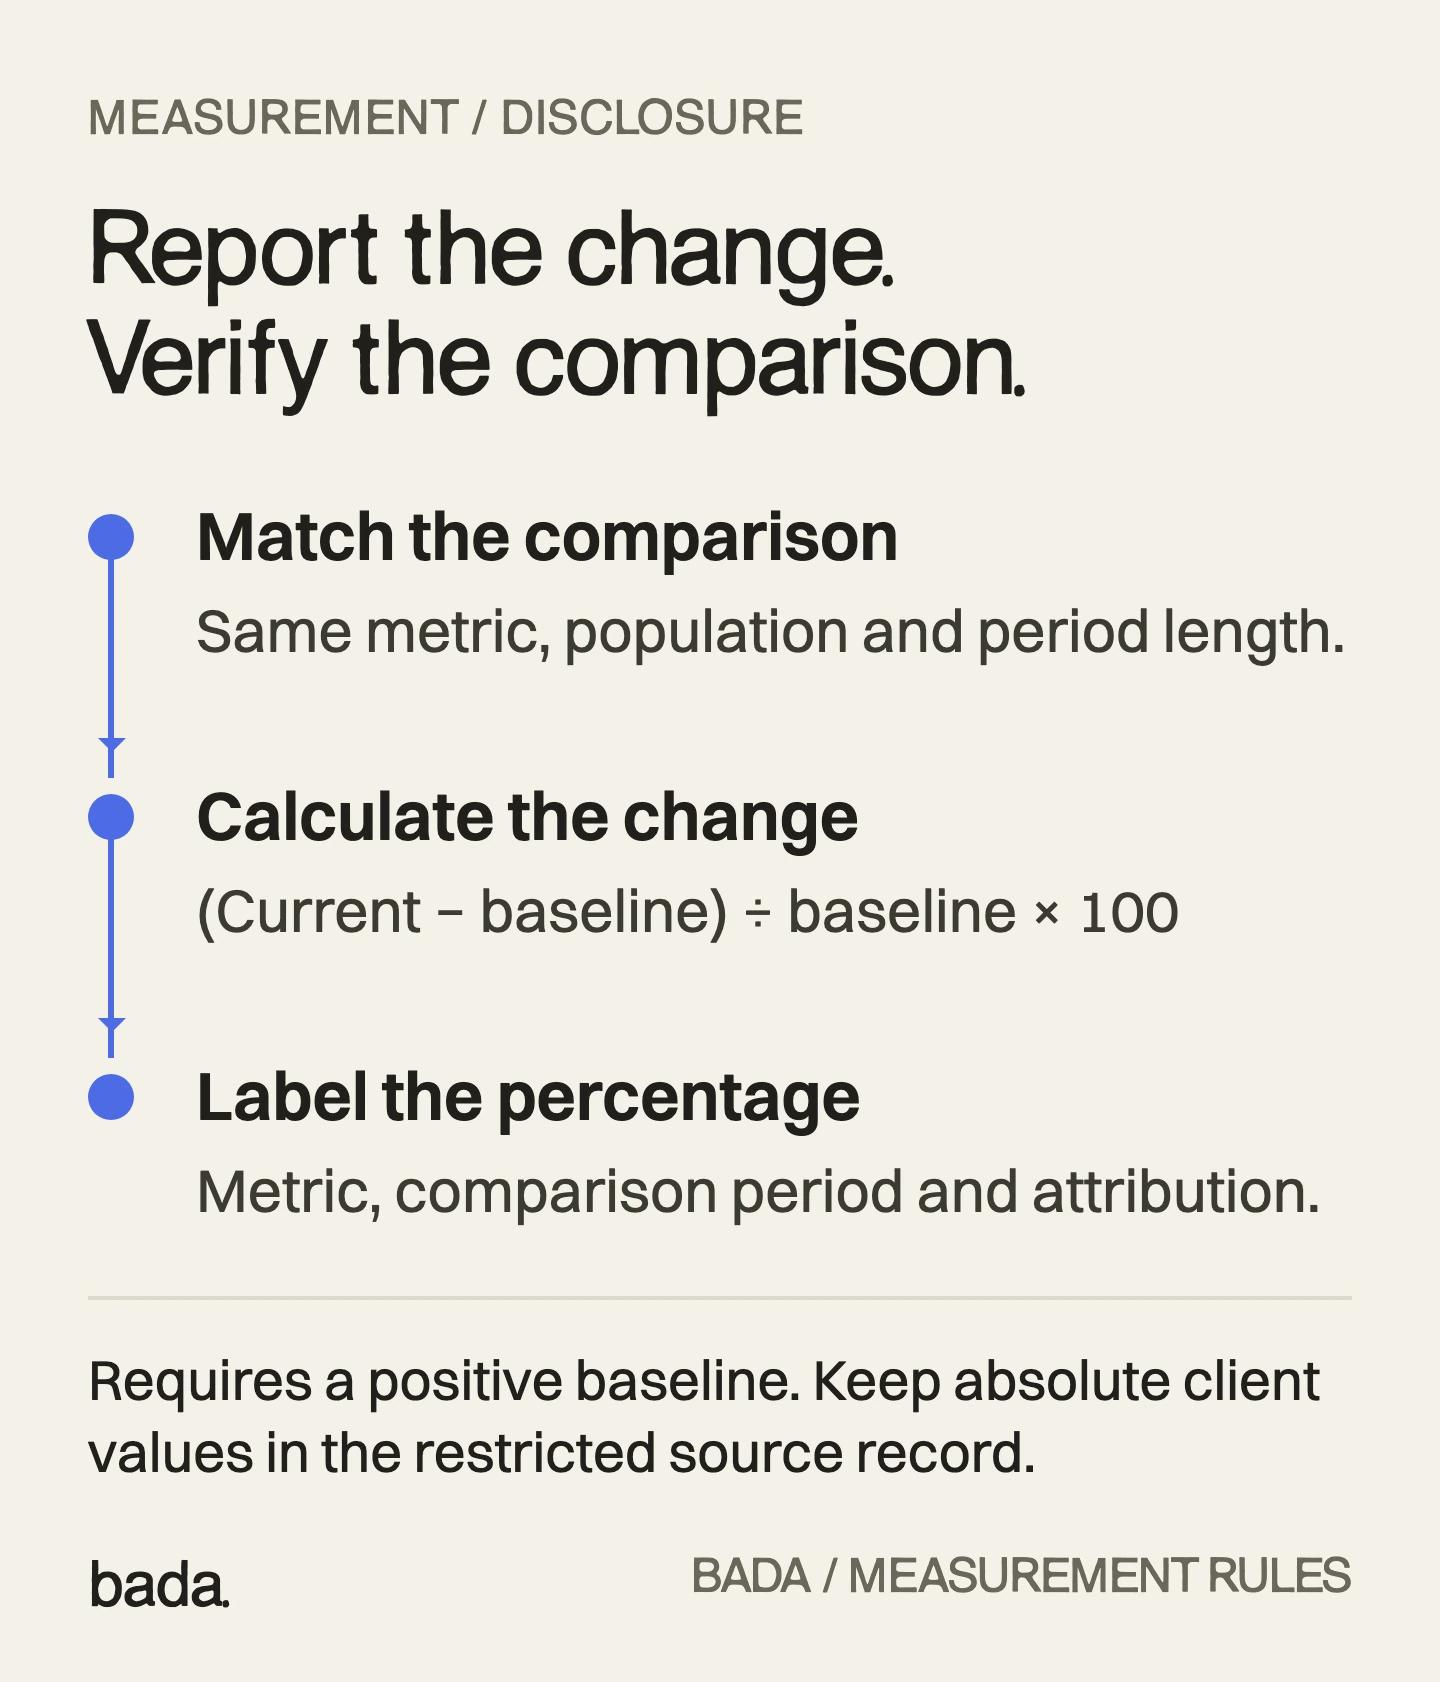
For a growth comparison, identify a baseline and an end value for the same metric. Match the period lengths, eligible population, attribution rules and measurement definitions. A program aggregate cannot substitute for acquisition-month rows or equal-age account histories.
- Keep measured media spend, influenced pipeline and won-influenced revenue in separate fields. Percentage changes in those fields answer different questions. Growth in influenced pipeline does not establish an equivalent increase in won business.
- To build the cohort view, join the eligible account's entry timestamp to its opportunity history, source assignment and outcome timestamps. State the reporting cutoff and calculate elapsed age from that entry event. Do not assign an acquisition month from the month a deal happened to close.
Reconcile the grouped rows back to the source report under the same filters and attribution rules. Keep unmatched accounts and unknown source records visible. Resolve a mismatch before using the rows to reallocate budget.
An account-to-opportunity rate needs an eligible account denominator. A decided-opportunity win rate needs won and lost opportunity counts. Keep the supporting counts in the restricted source record so the published percentage can be checked.
Publish the approved percentage change with its metric, comparison period and attribution scope. Retain the underlying absolute values in the restricted workpaper. Do not publish a percentage whose comparison cannot be reconstructed.
(4. Separate won, open, and influenced)
Preserve the definitions for open, won and lost opportunities. Inspect the linked CRM records before combining them, and keep each status visible in the internal reconciliation. A value-based pipeline measure does not supply a count-based win rate.
Count each eligible opportunity once within the chosen view. A decided-opportunity win rate uses won opportunities divided by won plus lost opportunities. Show still-open opportunities separately, along with their age and next action. Missing or unresolved outcomes cannot be silently classified as losses.
For an influenced report, inspect the qualifying interaction and when it happened. A webinar attended during an existing opportunity does not automatically become that opportunity's source. Keep sourced wins separate from influenced wins, and deduplicate opportunities before combining programs.
Recorded association does not establish that a touchpoint caused a sale. If incremental impact is the question, use an appropriate experimental or comparison design with its limitations documented.
(5. Recalculate the economics)
For a positive baseline, percentage change = (current value − baseline value) / baseline value × 100. Apply it to one consistently defined metric across comparable windows. A zero baseline has no defined percentage increase; disclose that limitation rather than manufacturing a result.
This calculation does not establish profit, incremental lift or a fully loaded return. Production, technology, sales effort, delivery costs, margin and cash timing need their own accounting. Media cost per won customer also requires a verified count of distinct won customers; the aggregate revenue figure cannot supply it.
When the actual cohort rows are available, calculate combined rates from combined compatible counts. Use total eligible outcomes divided by total eligible accounts, and show both counts. A simple average of percentages gives differently sized groups the same weight.
Inspect contract size, margin, and cash timing separately before judging affordability. Pipeline value belongs in its own field. It is not realized revenue.
(6. Assign the next action)
Read the account histories behind the change before choosing a fix.
- If suitable accounts enter but fail to reach accepted opportunities, review the teaching asset, follow-up, qualification, and sales response together.
- If opportunities progress but approvals remain open, ask sales for the next buyer-owned milestone and evidence that it is active.
- If mature cohorts produce unacceptable economics under complete cost accounting, revisit the audience, offer, delivery model, or channel allocation.
Record the decision, owner, evidence gap, and next review condition. Preserve the definitions and snapshot so the next meeting can test what changed.
For help connecting the report to an education-led acquisition system, bring the cohort rules and the decision currently blocked by the data. Get in touch.
Call us.
312-600-8001
Most companies own an acquisition asset they've never distributed. It's trapped in sales calls, support tickets, and one person's head. Send us a note about what you sell and who buys it.